FHA loss mitigation is the set of options an FHA loan servicer must review before it can foreclose. The FHA loss mitigation options are a repayment plan, forbearance, a partial claim, a loan modification, the Payment Supplement, a pre-foreclosure sale (an FHA short sale) and a deed-in-lieu. If none of them work, the home goes to a Colorado Public Trustee sale. If no outside bidder buys it there, the lender conveys it to HUD, and it becomes a HUD home.
This guide answers how FHA loss mitigation works, what each option does, how long a Colorado foreclosure takes and how a foreclosed FHA home ends up on the HUD Home Store. It is written for two readers: an FHA borrower who is behind on payments, and a buyer who wants to know where HUD homes come from. Questions? Call or text 303-955-4220.
What is FHA loss mitigation?
FHA loss mitigation is HUD’s required process for helping a borrower keep the home or leave it without a foreclosure. The servicer runs it, not HUD. The servicer is the company that sends your monthly statement.
HUD sets the rules in its Single Family Housing Policy Handbook. The servicer must review a borrower for every option in a set order, called the waterfall. Foreclosure comes only after that review.
How does FHA loss mitigation work, step by step?
- You miss a payment. The servicer must contact you and explain your options.
- You send a complete loss mitigation request. This means income, expenses, bank statements and a hardship letter.
- The servicer reviews you for home retention options first. These keep you in the home.
- Most modifications start with a Trial Payment Plan. You make three trial payments, then the change becomes permanent.
- If you cannot or do not want to keep the home, the servicer reviews you for a pre-foreclosure sale or a deed-in-lieu.
- If nothing works, the servicer can refer the loan to foreclosure.
Federal servicing rules bar the first foreclosure filing until a loan is more than 120 days delinquent. HUD’s 2026 update (Mortgagee Letter 2026-08) says the servicer must finish its review of your first complete request, and any later complete request after a change in your circumstances, before it starts foreclosure. The same update lets borrowers make trial payments early without penalty.
What are the FHA loss mitigation options?
| Option | What it does | Keep the home? |
|---|---|---|
| Repayment plan | Spreads the past-due amount over future payments. | Yes |
| Forbearance | Reduces or pauses payments for a set period. | Yes |
| Partial claim | HUD pays the arrears; you owe it back as a 0% second lien due at sale, refinance or payoff. | Yes |
| Loan modification | Changes the rate, term or balance to lower the payment. | Yes |
| Payment Supplement | Uses partial claim funds to cure arrears and lower the payment for three years. | Yes |
| Pre-foreclosure sale (FHA short sale) | You sell for less than you owe; HUD accepts the net. | No |
| Deed-in-lieu | You sign the home over to the lender instead of a foreclosure. | No |
What is an FHA partial claim, and how much can it cover?
A partial claim is a zero-interest loan from HUD that brings your mortgage current. It is recorded as a second lien. You make no monthly payments on it. You repay it when you sell, refinance or pay off the first mortgage.
All partial claims on one loan combined can reach up to 30% of the unpaid principal balance at the time of default.
What is the FHA Payment Supplement?
The Payment Supplement is built for borrowers with a low interest rate. A modification at today’s rates would raise their payment, not lower it. Instead, HUD uses partial claim funds to cure the arrears and pays part of the monthly payment for three years. Your original loan terms stay in place.
How often can I get FHA loss mitigation?
One permanent home retention option every 24 months. That covers a partial claim, a loan modification, a combination modification and partial claim, or a Payment Supplement. Borrowers hit by a Presidentially Declared Major Disaster can be exempt.
Can I do a short sale on an FHA loan?
Yes. HUD calls it a Pre-Foreclosure Sale. HUD accepts a sale where the net proceeds meet a minimum based on the appraised value:
- 88% of appraised value in the first 30 days of marketing
- 86% in days 31 to 60
- 84% after day 60
A seller who closes can receive relocation help of up to $3,000. The seller owes no commission out of pocket. Owners anywhere in Colorado can start with short sale help on the main site.
What is a deed-in-lieu on an FHA loan?
A deed-in-lieu of foreclosure means you hand the home to the lender and walk away from the loan. The home usually has to be free of other liens. It is an option when a short sale does not close. HUD offers consideration of up to $3,000 for a completed deed-in-lieu.
How long does a foreclosure take in Colorado?
Colorado uses a non-judicial process run by the county Public Trustee. After the lender records a Notice of Election and Demand, the sale is usually set 110 to 125 days later. The owner can cure the default before the sale by filing a written notice of intent to cure. Loss mitigation review and postponements often push the sale back.
Does applying for loss mitigation stop a Colorado foreclosure?
A complete application sent early gives you the strongest protection. Servicers cannot move to a foreclosure sale while a complete application received in time is still under review. An incomplete application does not get that protection. Send every page the servicer asks for, and keep proof you sent it.
How does a foreclosed FHA home become a HUD home?
At the Public Trustee sale, the lender bids. If an outside buyer outbids the lender, that buyer gets the home. If not, the lender takes title, conveys the home to HUD and files an insurance claim. HUD’s Colorado asset manager, Raine and Company, then lists it on the HUD Home Store through a HUD-registered listing broker.
Owner-occupant buyers get the first 15 days to bid on insured homes and 5 days on uninsured homes. After that, investors can bid. See the Colorado HUD homes for sale and the Colorado HUD inventory report for what is listed now.
HUD homes available now in metro Denver
Pulled from HUD’s live inventory and refreshed twice a day. Bid deadlines move and homes drop off the day a bid is accepted, so confirm any of these with us before you plan around it. Only a HUD-registered agent can place your bid. That is us; ask how buyer-broker compensation works for the property.
1575 S Trenton Ct
Denver, Denver County · 3 bed · 2 bath · IE$100 down
$480,000
4374 W Pondview Dr
Littleton, Arapahoe County · 2 bed · 2 bath · IE$100 down
$370,000
10351 W Girton Dr Unit 2
Lakewood, Jefferson County · 2 bed · 2 bath · IN$100 down
$302,600
1625 Verbena St
Denver, Denver County · 2 bed · 1 bath · IE$100 down
$260,000
1030 S Zeno Way
Aurora, Arapahoe County · 3 bed · 3 bath · IE$100 down
$250,500
1608 Oakland St
Aurora, Adams County · 2 bed · 1 bath · IE$100 down
$244,000
8600 E Alameda Ave #19-108
Denver, Denver County · 2 bed · 2 bath · IE$100 down
$228,000
17113 E Ford Drive
Aurora, Arapahoe County · 2 bed · 2 bath · IE$100 down
$200,000
3550 S Harlan Street Unit 242
Denver, Denver County · 2 bed · 2 bath · IN$100 down
$191,000
17670 E Loyola Dr Unit B
Aurora, Arapahoe County · 1 bed · 1 bath · IN$100 down
$136,000
495 South Dayton St Unit# 1c
Denver, Denver County · 2 bed · 1 bath · IN$100 down
$116,000
2231 South Vaughn Way Unit 111b
Aurora, Arapahoe County · 1 bed · 1 bath · IE$100 down
$78,400
Every home above is a verified HUD-owned listing, checked against HUD Home Store on Oct 15, 2026 8:21 pm Mountain time. Official source: HUD Home Store guidance at hud.gov; if anything differs, the federal listing controls.
8 more across Colorado, from Fountain to Pueblo to the Eastern Plains. See every HUD home in the state, or call or text 303-955-4220 and we will tell you which ones are worth a look.
What should a buyer take from this?
Every HUD home went through this process first. Many sat vacant during it. That is why HUD homes sell as-is and often need work. A 203(k) loan can finance repairs, and HUD pays up to 3% of closing costs when a buyer requests it in the bid. Read how to buy a HUD home and the HUD financing guide before you bid.
Behind on an FHA loan, or ready to bid on a HUD home? The Kenna Real Estate Group at Keller Williams DTC has 4.9 stars from 332 reviews.
A live person answers.
FHA loss mitigation FAQ
Who handles FHA loss mitigation, HUD or my servicer?
Your servicer. HUD sets the rules, and the servicer reviews you and approves the option.
How much can an FHA partial claim cover?
All partial claims on one loan combined can reach up to 30% of the unpaid principal balance at the time of default. It is a 0% second lien with no monthly payment.
How often can I get an FHA loan modification or partial claim?
One permanent home retention option every 24 months, unless a Presidentially Declared Major Disaster applies.
What does HUD require for an FHA short sale?
Net proceeds of at least 88% of appraised value in the first 30 days, 86% in days 31 to 60 and 84% after day 60. Sellers can receive up to $3,000 for relocation.
How long does a Colorado foreclosure take?
The Public Trustee sale is usually set 110 to 125 days after the Notice of Election and Demand is recorded. Loss mitigation review often adds time.
How does a foreclosed FHA home become a HUD home?
If no outside bidder buys it at the Public Trustee sale, the lender takes title and conveys it to HUD. Raine and Company then lists it on the HUD Home Store.
Where to go next
- What is a HUD home?
- FHA short sales in Colorado
- Colorado HUD homes for sale
- HUD home FAQs
- Find a HUD-registered agent
- HUD listing broker in Colorado
Call or text 303-955-4220. A live person answers.
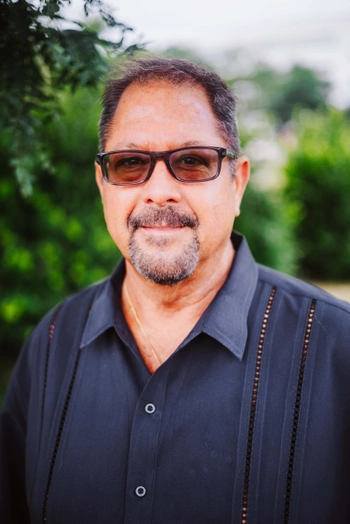
Written and reviewed by
Brian Lee Burke, Colorado HUD home specialist and team leader
Licensed Colorado real estate professional since 2003 · REALTOR® · Team leader and licensed broker of the Kenna Real Estate Group at Keller Williams DTC, a group that regularly bids on HUD homes through Keller Williams Realty DTC, LLC, a HUD-registered brokerage · Author of The Real Estate Playbook and Mastering Real Estate. Brian’s full HUD biography.
Last reviewed: October 15, 2026 · Sources: HUD Home Store (hudhomestore.gov) and HUD program guidance, HUD Handbook 4000.1, REcolorado MLS data via kennarealestate.com, and the Kenna Real Estate Group’s own HUD transaction files.
Contact: call or text 303-955-4220 or homes@kennarealestate.com. During office hours you reach a live local Kenna real estate professional, not a robot or a national call center. Brokerage: Keller Williams Realty DTC, LLC (the Kenna Real Estate Group is a group of brokers there), 6300 S Syracuse Way, Suite 150, Centennial, CO 80111. Each Keller Williams office is independently owned and operated. The Kenna Real Estate Group is an independent real estate team and is not affiliated with or endorsed by HUD or any government agency; official property information comes from HUD Home Store. Equal Housing Opportunity.
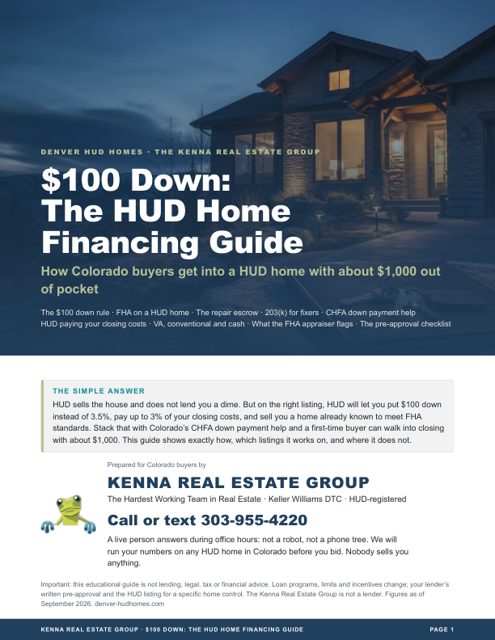
Free guide, PDF
$100 Down: The HUD Home Financing Guide
The $100 down rule, CHFA, HUD paying your closing costs: the stack that gets a buyer in for about $1,000. 14 pages, free.
Why you want it before you bid:
- Which listings qualify for $100 down and how to spot them (the IN and IE codes)
- What you still pay at closing, line by line, with a real example
- How $100 down stacks with CHFA, metroDPA and Good Neighbor Next Door
Find every home available, not just HUD homes
Advanced home search: every listing on the Colorado MLS, with the full filters, on kennarealestate.com.
Opens kennarealestate.com, the Kenna Real Estate Group’s full MLS search. HUD homes only? Use the tiles and the map on this site.
Ask us about HUD homes
Tell us what you are working with and we will tell you honestly whether a HUD home is the way to get there. No cost, no obligation, and nobody sells you anything.
Call or text 303-955-4220
A live person answers. Not a robot, not a phone tree.