The lender we know, like and trust
The lender we trust with HUD buyers: Mike OswaldVP of Mortgage Lending at Rate
A HUD bid dies at the appraisal or at the pre-approval more often than anywhere else. Mike Oswald has been lending to Colorado families since 2001, knows what IN, IE and UI mean before you say them, and can turn a pre-approval fast enough to make a 15-day bid window. He is not our employee, we are not paid when you use him, and you are free to use any lender you want. We introduce buyers to Mike because the deals close.
Mike answers his cell: (303) 917-6737. For the home itself, call or text us at 303-955-4220.
Thousands of Colorado closings
Purchase and refinance, first-time buyers to jumbo. A quarter century of Front Range loans.
FHA, 203(k), VA, USDA, DPA
The exact loans HUD buyers need, including down payment assistance layered on FHA.
Same-Day Mortgage program
Rate’s fast-track underwriting. On a sealed-bid window, speed is the whole game.
Parker, Colorado
Colorado native. Office at 1221 S Clarkson St, Denver. Answers his cell.
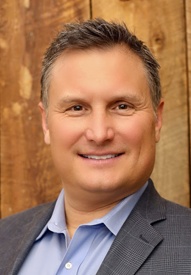
Meet Mike Oswald
Vice President of Mortgage Lending at Rate · NMLS 261003 · Lending to Colorado families since 2001
Mike has guided thousands of Colorado buyers through purchases and refinances over 25 years, and HUD homes are a specialty: he reads the IN, IE and UI codes before you send the listing, knows what an FHA appraiser will flag, and turns real pre-approvals fast enough to make a 15-day bid window. He is a Colorado native based in Parker, married with three daughters, a Broncos fan who hikes, fly fishes and golfs. His philosophy, in his words, is to be the gift and bring encouragement to every client. Office: 1221 S Clarkson St, Suite 301, Denver.
Rate, Inc. NMLS 2611. Equal Housing Lender. You may use any lender you choose; the Kenna Real Estate Group is not a lender and receives nothing for this introduction.
National averages for conforming loans with 20% down and strong credit; FHA and 203(k) rates on a HUD home will differ. Your rate depends on the loan, your credit and the day you lock. Get a real quote from Mike Oswald at Rate, or read what these numbers mean for a HUD purchase.
Why a HUD home needs a lender who has done this before
HUD does not care who your lender is. HUD cares whether your loan closes on the date in the contract, and it keeps your earnest money if it does not. That puts the lender at the center of every HUD purchase in three places.
- The pre-approval has to be real. An owner-occupant window is 15 days. A pre-qualification letter from a website is not going to hold up when HUD asks for the file. Mike issues pre-approvals with the income and credit already verified.
- The loan has to match the listing code. Insured homes take a standard FHA loan. Insured-with-escrow homes take FHA plus a repair escrow. Uninsured homes need a 203(k) or a renovation loan. Bid with the wrong one and the appraisal kills the deal. The codes, explained.
- The appraisal has to be handled. FHA appraisers flag roofs, peeling paint, missing handrails. A lender who works HUD homes knows what will get flagged and how the escrow or 203(k) covers it, before it becomes a problem.
The loans Mike does that HUD buyers actually use
- FHA. 3.5% down, flexible credit, the default for owner-occupant HUD buyers. What an FHA loan is.
- FHA 203(k). Purchase plus repairs in one loan, for the uninsured fixers in Englewood and Littleton. How a 203(k) works on a HUD home.
- Down payment assistance. CHFA and local programs stacked on FHA, which is how buyers get to about $1,000 cash to close. CHFA down payment assistance.
- VA. Zero down for veterans and service members on insured HUD homes. Colorado VA loans.
- USDA. Zero down in eligible rural areas, which covers a surprising amount of the Colorado HUD inventory outside the metro.
- Conventional and jumbo. For buyers with stronger credit or higher-priced homes; FHA versus conventional is the comparison to read first, and conventional renovation products can cover some uninsured homes.
- Same-Day Mortgage. Rate’s accelerated approval program. If a home you want shows up on a Wednesday and the window closes the next week, this is what makes the bid possible.
Why Rate, and why it matters on a HUD deal
Rate is the lender formerly known as Guaranteed Rate. It launched in 2000, is headquartered in Chicago, runs more than 850 branches across all 50 states, and has helped more than 2 million homeowners buy or refinance. Fortune named Rate a Best Mortgage Lender of 2025 and Best Overall for its online mortgage experience; Forbes named it a 2025 Best Mortgage Lender for first-time buyers; NerdWallet ranks it among the best for FHA loans and for lower credit scores; Inside Mortgage Finance put it in the top five U.S. mortgage lenders for 2024.
For a HUD buyer, two of those matter more than the trophies. FHA depth: most Colorado HUD purchases are FHA or 203(k), and Rate is one of the highest-volume FHA lenders in the country, so the underwriting does not get surprised by a HUD contract. Speed: Rate’s Same-Day Mortgage program can issue approvals in a day and close in as little as 10 days, which is what a sealed-bid window with a hard closing date actually requires.
How to work with Mike on a HUD purchase
- Call or text him at (303) 917-6737, or start the pre-approval online, which goes straight to Mike. Tell him it is a HUD home and which city.
- Get the real pre-approval before the bid window, not during it. Why that matters.
- Loop us in. Call or text 303-955-4220. We place the bid, Mike closes the loan, and the two sides talk to each other so nothing falls through the gap.
About Mike
Mike Oswald is Vice President of Mortgage Lending at Rate, NMLS 261003, and has served Colorado families as a mortgage loan officer since 2001. He is a Colorado native based in Parker, married with three daughters, a Broncos fan who hikes, fly fishes and golfs when he is not closing loans. His office is at 1221 S Clarkson St, Suite 301, Denver, CO 80210. His philosophy, in his words, is to be the gift, bringing encouragement to every client.
Where to go next
- Financing a HUD home: IN, IE, UI and which loan fits
- Good Neighbor Next Door: 50% off for teachers, police, fire and EMTs
- How to buy a HUD home
- Find a HUD-registered agent
- HUD homes for sale by city
- Mortgage calculator
- Colorado first-time buyer programs
- Financing options on our main site
- HUD home FAQs
- The truth about $1 HUD homes
Your choice of lender. You are not required to use Mike Oswald, Rate, or any lender we mention to buy a HUD home or to work with the Kenna Real Estate Group. Shop around; compare rates, fees and service. The Kenna Real Estate Group has no ownership interest in Rate, receives no referral fee, payment or other thing of value from Rate or Mike Oswald, and Mike is not our employee. We name him because our clients have had good experiences with him. Rate, Inc. NMLS 2611, Equal Housing Lender. Loan programs, rates and eligibility are set by the lender and change; confirm current terms with the lender directly.
Free guide, PDF
$100 Down: The HUD Home Financing Guide
The $100 down rule, CHFA, HUD paying your closing costs: the stack that gets a buyer in for about $1,000. 14 pages, free.
Get the free guideInstant download. We email you a copy too. No spam, ever.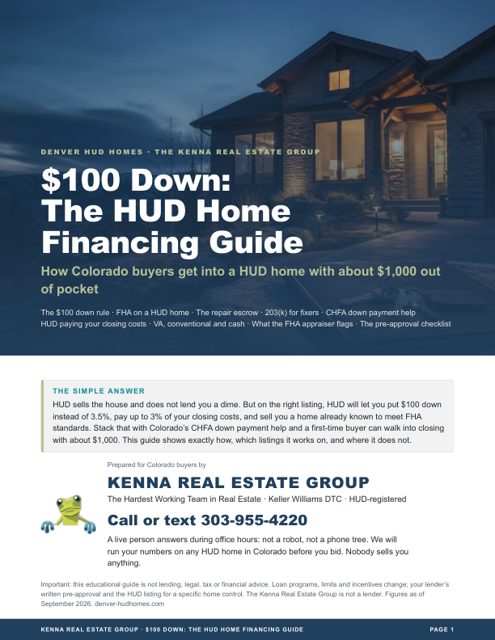
Find every home available, not just HUD homes
Advanced home search: every listing on the Colorado MLS, with the full filters, on kennarealestate.com.
Opens kennarealestate.com, the Kenna Real Estate Group’s full MLS search. HUD homes only? Use the tiles and the map on this site.
Ask us about financing with Mike Oswald
Tell us what you are working with. We will loop Mike in if you want him, or you can use any lender you like. No cost, no obligation, and nobody sells you anything.
Call or text Mike (303) 917-6737
Or start the pre-approval online. For the home itself, we are at 303-955-4220.