Financing
How to finance a HUD home in Colorado
HUD sells the house. HUD does not lend you the money. The financing is on you, and the letters on the listing decide which loans will work. This page walks through FHA, 203(k), CHFA down payment help, VA, conventional and cash, in plain terms, so you know what you can actually bid with before the window opens.
Call or text 303-955-4220 and a live person answers. Not a robot, not a phone tree.
Insured, escrow, or uninsured
IN means FHA will insure it as-is. IE means FHA will insure it with a small repair escrow. UI means it needs too much work for a standard FHA loan. That one line decides your loan.
FHA with 3.5% down
Most Colorado HUD buyers use an FHA loan. Low down payment, and the home is often already FHA-insurable, which is the whole point of the IN label.
FHA 203(k)
Rolls the repair cost into the mortgage. On an uninsured HUD home this is usually the only financed path that works.
CHFA stacks on top
Colorado’s CHFA programs can cover part of the down payment and pair with FHA on a HUD purchase. Income limits apply.
30-yr fixed 6.95% · 15-yr 6.26% this week what it means for a HUD home
Get pre-approved with Mike Oswald, VP of Mortgage Lending at Rate · NMLS 261003 · HUD files every week · you may use any lender
National averages for conforming loans with 20% down and strong credit; FHA and 203(k) rates on a HUD home will differ. Your rate depends on the loan, your credit and the day you lock. Get a real quote from Mike Oswald at Rate, or read what these numbers mean for a HUD purchase.
Start with a lender who knows HUD homes
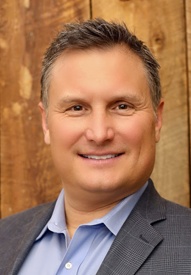
Meet Mike Oswald
Vice President of Mortgage Lending at Rate · NMLS 261003 · Lending to Colorado families since 2001
Mike has guided thousands of Colorado buyers through purchases and refinances over 25 years, and HUD homes are a specialty: he reads the IN, IE and UI codes before you send the listing, knows what an FHA appraiser will flag, and turns real pre-approvals fast enough to make a 15-day bid window. He is a Colorado native based in Parker, married with three daughters, a Broncos fan who hikes, fly fishes and golfs. His philosophy, in his words, is to be the gift and bring encouragement to every client. Office: 1221 S Clarkson St, Suite 301, Denver.
Rate, Inc. NMLS 2611. Equal Housing Lender. You may use any lender you choose; the Kenna Real Estate Group is not a lender and receives nothing for this introduction.
Start with the listing code, not the lender
Every HUD listing carries a financing code, and it is the most important thing on the page.
- IN, insured. HUD’s appraiser found the home meets FHA minimum property standards as it sits. A standard FHA loan works. So does conventional, VA or cash.
- IE, insured with escrow. The home needs a short list of repairs to meet FHA standards. HUD sets an escrow amount, the lender holds it, and the work is done after closing. Standard FHA still works, with the escrow added.
- UI, uninsured. The repairs exceed what an escrow can cover. A standard FHA loan will not work. Your options are FHA 203(k), a conventional renovation loan, or cash.
If you bid on a UI home with a standard FHA pre-approval, you will win the bid and lose the house at the appraisal. It happens every month. Match the loan to the code before you bid.
FHA: the default loan for Colorado HUD home buyers
FHA loans require 3.5% down, allow lower credit scores than conventional, and are what most owner-occupant HUD buyers in Colorado use. Because HUD is the agency behind FHA, an insured HUD home is already known to meet FHA standards, which removes the biggest risk in the appraisal. What an FHA loan is and how it works in Denver covers the details, and FHA versus conventional helps you decide if you qualify for both.
203(k): when the house needs work
The FHA 203(k) loan lets you borrow the purchase price plus the cost of repairs in one mortgage, based on what the home will be worth after the work. On an uninsured HUD home, or an older home in Englewood or Littleton that needs a roof and a sewer line, this is usually the only financed path. It takes longer, needs a contractor bid before closing, and the lender has to offer it. Turning a HUD fixer into a livable home walks through the whole thing.
CHFA and down payment assistance
The Colorado Housing and Finance Authority runs down payment assistance that can be layered on top of an FHA loan. Income limits and a homebuyer class apply, but for a lot of first-time buyers CHFA is the difference between bidding and watching. CHFA down payment assistance explained and using CHFA and FHA together on a HUD home cover it from both sides. Denver and several counties also run their own programs; local down payment help that pairs with a HUD purchase lists them.
The $100 down incentive
On some FHA-financed, owner-occupant purchases HUD offers a $100 down payment instead of the usual 3.5%. It is not on every listing and it comes and goes by region. Ask whether the home you are looking at carries it; if it does, it changes the whole budget.
$1,000 cash to close: how Colorado buyers actually do it
Cash to close is everything you bring to the closing table: down payment plus closing costs. On a $350,000 HUD home with FHA that is normally about $12,000 down plus $8,000 to $10,000 in costs. The way Colorado buyers get that number down to about $1,000 is by stacking three things.
- CHFA covers most of the down payment. Colorado’s housing finance authority offers down payment assistance as a grant or a silent second loan for buyers under its income limits with a 620 or better score. How CHFA down payment assistance works.
- HUD pays closing costs. You can ask HUD for up to 3% of the price toward closing costs, written into the bid. It lowers HUD’s net, so use it on a home that has sat rather than a brand-new listing.
- The $100 down incentive, when it exists. On some FHA-financed owner-occupant HUD purchases the down payment drops to $100. Ask about the specific home.
Put those together on the right listing and a first-time buyer walks in with about $1,000 and walks out with keys. It is not every home and not every buyer, but it is real, and we have done it. Call or text 303-955-4220 and we will run your numbers before you bid, not after.
VA, conventional and cash on a HUD home
- VA. Zero down for eligible veterans and service members. Works on insured HUD homes; the VA appraisal has its own standards. Colorado VA loans has more.
- Conventional. Usually 5% down and a higher credit bar. Works on insured homes and, with a renovation product, on some uninsured ones.
- Cash. Works on everything and closes fastest. HUD still runs the same bid window, so cash does not let you skip the line during the owner-occupant period.
Get pre-approved before the window opens
A HUD bid window on an insured home is 15 days for owner-occupants. You cannot start a loan application on day 12 and expect a pre-approval letter by day 15. Get it done first. Why pre-approval matters, and run the payment so your bid is a number you can live with.
Where to go next
- How to buy a HUD home
- Buying a HUD home on a budget
- How to find and finance a HUD home in Denver
- First-time buyer guide to HUD homes
- Financing resources on our main site
- Find a HUD-registered agent
- Good Neighbor Next Door
Ready to talk to someone?
Call or text 303-955-4220. A live person answers. Tell us what you are working with and we will tell you honestly whether a HUD home is the way to get there.
Free guide, PDF
$100 Down: The HUD Home Financing Guide
The $100 down rule, CHFA, HUD paying your closing costs: the stack that gets a buyer in for about $1,000. 14 pages, free.
Get the free guideInstant download. We email you a copy too. No spam, ever.
Find every home available, not just HUD homes
Advanced home search: every listing on the Colorado MLS, with the full filters, on kennarealestate.com.
Opens kennarealestate.com, the Kenna Real Estate Group’s full MLS search. HUD homes only? Use the tiles and the map on this site.
Ask us about financing a HUD home
Tell us what you are working with and we will tell you honestly whether a HUD home is the way to get there. No cost, no obligation, and nobody sells you anything.
Call or text 303-955-4220
A live person answers. Not a robot, not a phone tree.