Most of the HUD homes that sit are the ones a standard FHA loan cannot close on: the UI and UK codes, the houses that need a roof or a furnace or a bathroom before FHA will insure them. The FHA 203(k) loan exists for exactly those houses. It funds the purchase and the repairs in one mortgage, with 3.5 percent down, and the work happens after closing.
Which HUD homes qualify
Any HUD home that FHA would insure once repaired, which in practice means UK homes (flagged 203(k) eligible on the listing) and many UI homes. IN and IE homes usually do not need a 203(k), though you can use one to add improvements beyond the required repairs. Condos and manufactured homes have extra rules; see FHA condo approval and manufactured HUD homes.
Limited versus Standard 203(k)
- Limited 203(k): non-structural repairs up to FHA’s current cap (raised in recent years; your lender quotes the figure). Roof, furnace, water heater, kitchens and baths, flooring, paint, windows. No consultant required, simpler paperwork, faster.
- Standard 203(k): structural work, additions, foundation, anything over the Limited cap, and any project that needs plans. A HUD-approved 203(k) consultant writes the work write-up, and draws are inspected as the work goes.
The timeline against HUD’s deadlines
This is where 203(k) purchases of HUD homes fail. HUD gives you about 45 days to close a financed purchase. A 203(k) needs contractor bids, sometimes a consultant’s inspection, and an appraisal based on the after-repair value. Every one of those steps needs access to the house, and the house has no utilities until you activate them. The order that works:
- Before bidding: pre-approval specifically for a 203(k), a contractor lined up, and a walk-through with the contractor so the bid you submit already reflects a rough repair number.
- Days 1 to 15 after acceptance: utilities on, inspection, consultant visit if Standard, contractor bid finalized.
- Days 15 to 40: appraisal, underwriting, closing package.
- Before day 45: if anything is short, request the 15-day extension with the lender letter. Extension rules.
After closing
The repair funds sit in an escrow with the lender. The contractor is paid in draws as work is completed and inspected. Work generally must start within 30 days of closing and finish within six months; you may finance up to six months of mortgage payments if the house is not livable during the work. You must occupy the home as your primary residence.
Down payment help stacks
CHFA and metroDPA down-payment assistance can be used with a 203(k) on a HUD home, subject to each program’s rules. Using CHFA and FHA together and down payment assistance for HUD purchases.
Where it goes wrong
A lender who has not closed a 203(k) recently, a contractor who will not commit to a bid until after closing, and an appraisal that comes in under the purchase price plus repairs. All three are avoidable by starting before the bid, not after. Mike Oswald at Rate closes 203(k) loans regularly and will tell you on the first call whether the house and the number work; you may use any lender you like.
Questions people ask next
Can I do the 203(k) repairs myself?
Generally no. HUD requires licensed contractors for 203(k) work, and the draws are paid to the contractor after inspection. Sweat equity is not a 203(k) feature.
Do I need a 203(k) consultant?
For a Standard 203(k), yes; the consultant writes the work write-up and inspects draws. A Limited 203(k) does not require one, though some lenders still use one.
Can the 203(k) cover the repair escrow on an IE home?
An IE home usually does not need a 203(k); the repair escrow inside a standard FHA loan handles the required work. A 203(k) is for repairs beyond what the escrow allows or for improvements you choose to add.
What if the after-repair appraisal comes in low?
The loan is sized on the lesser of purchase price plus repairs or 110 percent of the after-repair value. If the appraisal is short you reduce the scope, bring cash, or, for an owner-occupant with a written denial, cancel with the earnest money returned.
The listing controls. HUD changes its procedures from time to time and every property has its own dates, codes and conditions on HUD Home Store. Where this page and the official listing or current HUD rules differ, the listing and HUD’s current rules control. We check this page regularly; ask us to confirm anything before you rely on it.
Looking at a specific HUD home? Call or text 303-955-4220. A HUD-registered agent answers, reads the listing with you, and the answer is free.
Written and reviewed by
Brian Lee Burke, Colorado HUD home specialist and team leader
Licensed Colorado real estate professional since 2002 · REALTOR® · Team leader and licensed broker of the Kenna Real Estate Group at Keller Williams DTC, a HUD-registered group that regularly bids on HUD homes · Author of The Real Estate Playbook and Mastering Real Estate. Brian’s full HUD biography.
Last reviewed: September 20, 2026 · Sources: HUD Home Store and HUD Handbook 4000.1, CHFA program guidelines, metroDPA program guidelines, Freddie Mac PMMS, and the county programs named on the page.
Lending content reviewed by Mike Oswald, VP of Mortgage Lending at Rate, NMLS 261003.
Program facts change. Eligibility varies by buyer and property; lender approval is required; program funding can run out; buyers may use any qualified lender; the Kenna Real Estate Group does not control HUD, CHFA or lender decisions. Verify the current terms with the program and your lender before you rely on them.
Contact: call or text 303-955-4220 or homes@kennarealestate.com. During office hours you reach a live local Kenna real estate professional, not a robot or a national call center. Brokerage: Kenna Real Estate Group at Keller Williams Realty DTC, LLC, 6300 S Syracuse Way, Suite 150, Centennial, CO 80111. Each Keller Williams office is independently owned and operated. The Kenna Real Estate Group is an independent real estate team and is not affiliated with or endorsed by HUD or any government agency; official property information comes from HUD Home Store. Equal Housing Opportunity.
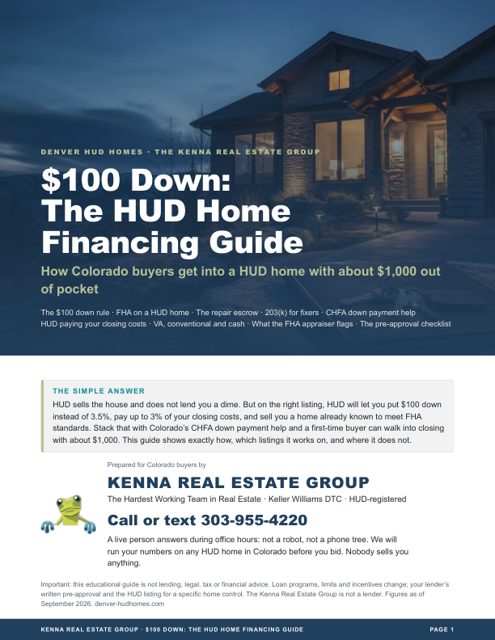
Free guide, PDF
$100 Down: The HUD Home Financing Guide
The $100 down rule, CHFA, HUD paying your closing costs: the stack that gets a buyer in for about $1,000. 14 pages, free.
Why you want it before you bid:
- Which listings qualify for $100 down and how to spot them (the IN and IE codes)
- What you still pay at closing, line by line, with a real example
- How $100 down stacks with CHFA, metroDPA and Good Neighbor Next Door
Find every home available, not just HUD homes
Advanced home search: every listing on the Colorado MLS, with the full filters, on kennarealestate.com.
Opens kennarealestate.com, the Kenna Real Estate Group’s full MLS search. HUD homes only? Use the tiles and the map on this site.
Ask us about HUD homes
Tell us what you are working with and we will tell you honestly whether a HUD home is the way to get there. No cost, no obligation, and nobody sells you anything.
Call or text 303-955-4220
A live person answers. Not a robot, not a phone tree.