People search “CHFA refinance no appraisal Colorado” every month, so let us be straight about it: CHFA does not offer refinance loans. The Colorado Housing and Finance Authority helps you buy a home, with a first mortgage and down-payment assistance. Once you own the home, any refinance goes through a regular lender.
What people usually mean
Most CHFA first mortgages are FHA loans. FHA has its own refinance with no appraisal, the FHA Streamline Refinance. If your CHFA loan is FHA-insured, that is the program you are actually looking for.
How the FHA Streamline works
- No appraisal in most cases. The new loan is based on your existing balance, not today’s value, so a soft market does not block it.
- No income re-verification on the non-credit-qualifying version, though the lender still checks your mortgage payment history.
- You must be current, with at least six payments made and 210 days since your original closing.
- Net tangible benefit: the refinance has to lower your rate and payment by a meaningful amount, or move you from an adjustable rate to a fixed one.
- Closing costs still exist. They cannot be rolled into a streamline loan, so you pay them at closing or take a slightly higher rate in exchange for a lender credit.
The catch with a CHFA second mortgage
If you used CHFA down-payment assistance, there is usually a second lien behind your first mortgage. Refinancing the first can trigger repayment of that second, or require CHFA to subordinate it. Ask before you apply; it changes the math.
VA and conventional owners
VA loans have their own no-appraisal option, the IRRRL. Conventional loans sometimes get an appraisal waiver from Fannie Mae or Freddie Mac when their data supports the value, but it is never guaranteed.
Who to call
Mike Oswald, VP of Mortgage Lending at Rate (NMLS 261003), handles CHFA purchase loans and FHA streamlines every week. Call or text (720) 677-5816. You may use any lender; the Kenna Real Estate Group receives nothing for the introduction.
Buying, not refinancing?
CHFA shines on the purchase side, especially stacked on an FHA loan for a HUD home. Start with CHFA down payment assistance on a HUD home and financing a HUD home in Colorado.
Written and reviewed by
Brian Lee Burke, Colorado HUD home specialist and team leader
Licensed Colorado real estate professional since 2002 · REALTOR® · Team leader and licensed broker of the Kenna Real Estate Group at Keller Williams DTC, a HUD-registered group that regularly bids on HUD homes · Author of The Real Estate Playbook and Mastering Real Estate. Brian’s full HUD biography.
Last reviewed: September 21, 2026 · Sources: HUD Home Store and HUD Handbook 4000.1, CHFA program guidelines, metroDPA program guidelines, Freddie Mac PMMS, and the county programs named on the page.
Lending content reviewed by Mike Oswald, VP of Mortgage Lending at Rate, NMLS 261003.
Program facts change. Eligibility varies by buyer and property; lender approval is required; program funding can run out; buyers may use any qualified lender; the Kenna Real Estate Group does not control HUD, CHFA or lender decisions. Verify the current terms with the program and your lender before you rely on them.
Contact: call or text 303-955-4220 or homes@kennarealestate.com. During office hours you reach a live local Kenna real estate professional, not a robot or a national call center. Brokerage: Kenna Real Estate Group at Keller Williams Realty DTC, LLC, 6300 S Syracuse Way, Suite 150, Centennial, CO 80111. Each Keller Williams office is independently owned and operated. The Kenna Real Estate Group is an independent real estate team and is not affiliated with or endorsed by HUD or any government agency; official property information comes from HUD Home Store. Equal Housing Opportunity.
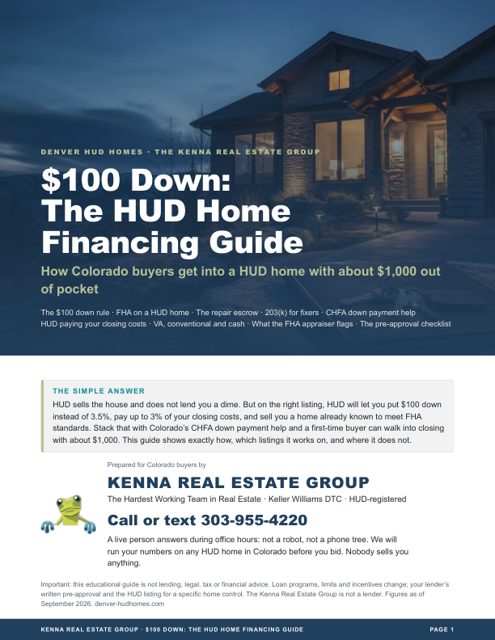
Free guide, PDF
$100 Down: The HUD Home Financing Guide
The $100 down rule, CHFA, HUD paying your closing costs: the stack that gets a buyer in for about $1,000. 14 pages, free.
Why you want it before you bid:
- Which listings qualify for $100 down and how to spot them (the IN and IE codes)
- What you still pay at closing, line by line, with a real example
- How $100 down stacks with CHFA, metroDPA and Good Neighbor Next Door
Find every home available, not just HUD homes
Advanced home search: every listing on the Colorado MLS, with the full filters, on kennarealestate.com.
Opens kennarealestate.com, the Kenna Real Estate Group’s full MLS search. HUD homes only? Use the tiles and the map on this site.
Ask us about HUD homes
Tell us what you are working with and we will tell you honestly whether a HUD home is the way to get there. No cost, no obligation, and nobody sells you anything.
Call or text 303-955-4220
A live person answers. Not a robot, not a phone tree.