Why an FHA loan is different when you fall behind
FHA does not own your loan. It insures it. That one fact changes everything about a short sale. Your servicer is not deciding how much money to lose; it is following HUD’s rulebook so the insurance claim gets paid. The rules are public, the thresholds are fixed, and the servicer has far less room to say no than a conventional lender does. It also means the clock is real: once the servicer has exhausted HUD’s loss mitigation ladder, it must move to foreclosure or lose its claim.
In Colorado, foreclosure moves through the county Public Trustee. From the Notice of Election and Demand to the sale is about 110 to 125 days. A short sale has to be approved and under contract inside that window, or the servicer has to agree to postpone the sale, which HUD allows when a PFS is in progress.
How the FHA Pre-Foreclosure Sale program works
- You have to be in default, or about to be. HUD’s PFS program is for borrowers who are behind, or who can show imminent default: a job loss, a divorce, a death, a medical event, a required move. You generally need to live in the home, though HUD allows non-occupant cases when the move was for work or the home was inherited.
- The servicer reviews you for everything else first. HUD requires the servicer to try to keep you in the home before approving a short sale: a repayment plan, a loan modification, a partial claim, or the FHA Payment Supplement. If none of those work, PFS is next.
- Approval to Participate. The servicer sends an Approval to Participate letter. It orders an FHA appraisal and states the list price and the minimum net HUD will accept. From that letter you have 120 days to market the home.
- The net proceeds tiers. HUD sets the floor as a percentage of the appraised value, and it drops the longer the home sits:
An offer that nets HUD at least that share of the appraised value, after commissions and closing costs, is approved. Below it, the offer is rejected unless the buyer comes up.
- Closing and relocation money. HUD pays the real estate commissions, the title work and up to $3,000 in relocation assistance to the seller in a standard PFS. The deficiency, the gap between what you owed and what the home sold for, is waived. No judgment, no collection.
- If it fails: deed-in-lieu, then a HUD home. A seller who cannot find a buyer inside 120 days can hand the keys back through a deed-in-lieu of foreclosure, with a smaller relocation payment. Either way the servicer conveys the house to HUD, files its insurance claim, and HUD lists the home on HUD Home Store. That is how a house becomes a HUD home, and it is why the Colorado HUD inventory grows a year or so after FHA defaults rise.
FHA short sale vs. conventional short sale vs. VA compromise sale
| FHA (HUD PFS) | Conventional (Fannie, Freddie, bank) | VA (compromise sale) | |
|---|---|---|---|
| Who sets the rules | HUD, in writing, the same for every servicer | The investor; varies by loan | VA regional loan center |
| Minimum net | 88% / 86% / 84% of appraised value by month | Negotiated; usually near market value | Net must cover VA’s guaranty math; VA approves case by case |
| Seller gets | Up to $3,000 relocation | Sometimes $3,000 to $10,000 under HAFA-style programs; often nothing | Usually nothing; VA may pay closing costs |
| Deficiency | Waived | Negotiated; can be pursued in Colorado | Waived if VA approves the compromise |
| Buy again with the same loan type | FHA: 3 years, less with documented extenuating circumstances | Conventional: 4 years, 2 with extenuating circumstances | VA: typically 2 years |
What an FHA short sale does to your credit and your next purchase
The servicer reports the account as settled for less than the full balance. The hit is smaller than a foreclosure and it ages faster. FHA will insure a new loan for you three years after the short sale closed, and sooner when the default was caused by something outside your control that you can document. If you kept every payment current until the sale, some lenders treat you as a no-waiting-period borrower. Buying a HUD home after a bankruptcy, foreclosure or short sale walks through the waiting periods lender by lender.
The Colorado-specific parts
- Public Trustee timeline. Colorado’s foreclosure is fast by national standards. Call your servicer the month you know you cannot pay, not the month the notice arrives.
- Deficiency law. Colorado lenders can pursue a deficiency after a conventional foreclosure. An FHA PFS approval closes that door in writing.
- Taxes. Forgiven mortgage debt can be taxable income. The Mortgage Forgiveness Debt Relief exclusion for a primary residence has lapsed and returned several times; ask a Colorado CPA which rule applies to your tax year before you sign.
- Who runs the file. The Kenna Real Estate Group lists FHA short sales across Denver and the Front Range and works with a lender-paid short sale negotiator, so the seller pays nothing for the negotiation. The buyer side of our business, this website, means we know exactly what HUD will accept because we see what HUD sells for every day.
Behind on an FHA loan right now? The order to do things in
- Call the servicer and ask for the loss mitigation department. Say the words “FHA Pre-Foreclosure Sale” if keeping the home is not realistic.
- Pull your mortgage statement, two pay stubs or your termination letter, two bank statements and last year’s tax return. That is the whole hardship package.
- Get a broker price opinion on the home before the servicer’s appraisal, so you know whether a sale at 88% of value clears the loan.
- List it the day the Approval to Participate arrives. The 120 days start then.
Or skip the research. Short sale help for Colorado homeowners and the Denver short sale page explain the seller side in full, and a call to 303-955-4220 gets you a broker who has closed them.
FHA short sale questions
Can I do an FHA short sale if I am current on my payments?
Yes, with documented imminent default: a hardship that makes the next payments impossible. HUD added imminent default to the PFS program so sellers do not have to ruin their credit before asking for help.
How long does an FHA short sale take in Colorado?
Plan on three to five months: a few weeks for the servicer’s review and appraisal, up to 120 days of marketing, then a 30 to 45 day closing. A well-priced Denver-area home usually goes under contract in the first month.
Will HUD approve a short sale to an investor or a relative?
Investors, yes, at arm’s length. Relatives, business partners and anyone with a prior interest in the home, no. The buyer and seller sign an arm’s-length affidavit, and the seller cannot stay in the home as a renter after closing.
Does an FHA short sale cost the seller anything?
No. HUD pays the commissions and the title and recording costs out of the sale, and a lender-paid negotiator handles the file. The seller walks away with the relocation payment, not a bill.
What happens if the only offer is below HUD’s minimum net?
The servicer counters or rejects it. After day 60 the floor drops to 84% of appraised value, and HUD can order a new appraisal if the market has moved. If nothing works by day 120, the deed-in-lieu option remains.
Talk to a broker who sells HUD homes and lists FHA short sales
Kenna Real Estate Group at Keller Williams DTC. HUD NAID MSTRSR6204.
Call or text. A live person answers.
Where to go next
Written and reviewed by
Brian Lee Burke, Colorado HUD home specialist and team leader
Licensed Colorado real estate professional since 2003 · REALTOR® · Team leader and licensed broker of the Kenna Real Estate Group at Keller Williams DTC, a group that regularly bids on HUD homes through Keller Williams Realty DTC, LLC, a HUD-registered brokerage · Author of The Real Estate Playbook and Mastering Real Estate. Brian’s full HUD biography.
Last reviewed: October 13, 2026 · Sources: HUD Home Store (hudhomestore.gov) and HUD program guidance, HUD Handbook 4000.1, REcolorado MLS data via kennarealestate.com, and the Kenna Real Estate Group’s own HUD transaction files.
Contact: call or text 303-955-4220 or homes@kennarealestate.com. During office hours you reach a live local Kenna real estate professional, not a robot or a national call center. Brokerage: Keller Williams Realty DTC, LLC (the Kenna Real Estate Group is a group of brokers there), 6300 S Syracuse Way, Suite 150, Centennial, CO 80111. Each Keller Williams office is independently owned and operated. The Kenna Real Estate Group is an independent real estate team and is not affiliated with or endorsed by HUD or any government agency; official property information comes from HUD Home Store. Equal Housing Opportunity.
Free guide, PDF
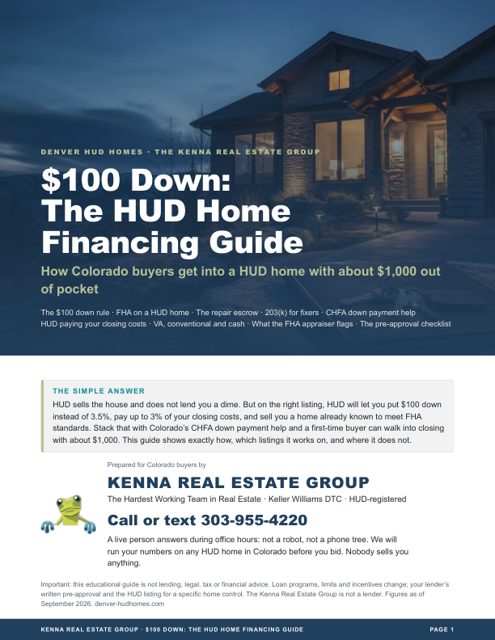
$100 Down: The HUD Home Financing Guide
The $100 down rule, CHFA, HUD paying your closing costs: the stack that gets a buyer in for about $1,000. 14 pages, free.
Why you want it before you bid:
- Which listings qualify for $100 down and how to spot them (the IN and IE codes)
- What you still pay at closing, line by line, with a real example
- How $100 down stacks with CHFA, metroDPA and Good Neighbor Next Door
Find every home available, not just HUD homes
Advanced home search: every listing on the Colorado MLS, with the full filters, on kennarealestate.com.
Opens kennarealestate.com, the Kenna Real Estate Group’s full MLS search. HUD homes only? Use the tiles and the map on this site.
Ask us about HUD homes
Tell us what you are working with and we will tell you honestly whether a HUD home is the way to get there. No cost, no obligation, and nobody sells you anything.
Call or text 303-955-4220
A live person answers. Not a robot, not a phone tree.