Short answer: an FHA foreclosure in Colorado runs on two clocks. HUD’s 2026 rules decide when the servicer may start, and Colorado’s Public Trustee process decides when the sale happens: 110 to 125 days after the notice of default is recorded. HUD’s FY2026 report counted 2,567 FHA foreclosure starts and 722 FHA foreclosure sales in Colorado, with an average of 6 months in foreclosure. Here is the full FHA foreclosure timeline, what to do at each step, and when a foreclosed home near you in Denver, Aurora or Colorado Springs can become a HUD home. Call or text 303-955-4220. A live person answers.
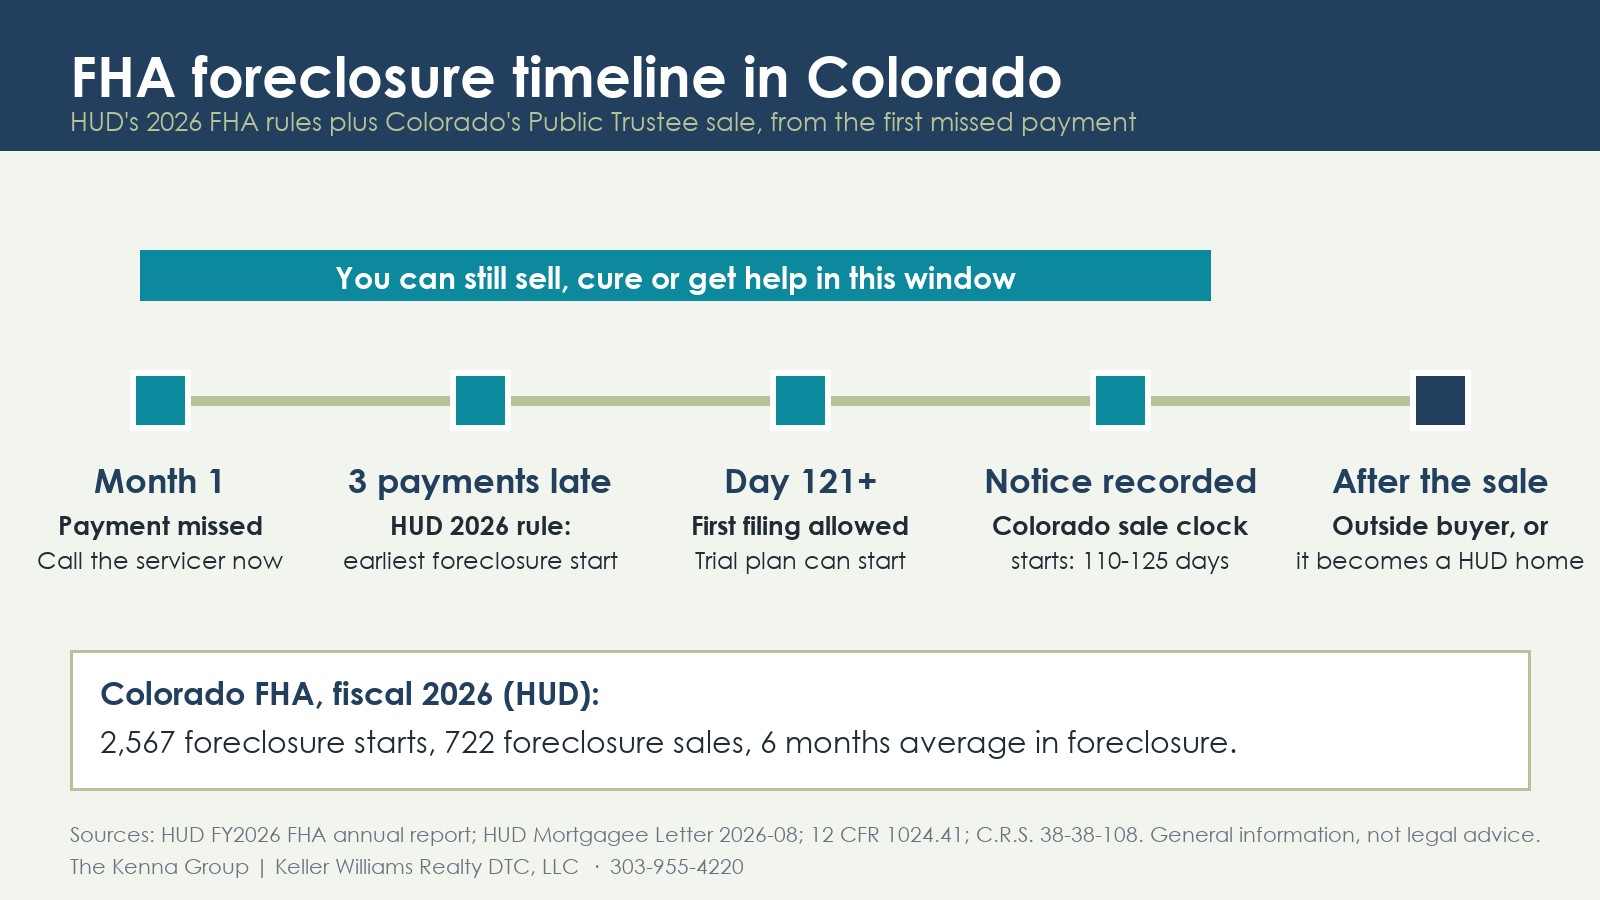
The FHA foreclosure timeline in Colorado, step by step
Counted from the first missed payment. HUD sets the federal part; Colorado law sets the sale.
What changed for FHA borrowers in 2026
- Trial payment plan first. HUD now requires a trial plan before a permanent modification or partial claim.
- One rescue every 24 months. A borrower gets one home-retention option in a 24-month window.
- Fewer delays. Mortgagee Letter 2026-08 limits repeat review requests, and refusing a trial plan a third time in the same default counts as a failure. Servicers had to follow it by September 21, 2026.
- Coming in FY2027: HUD plans a partial-claim change called the Reinstatement Advance Payment. It is a draft, not final.
For the options themselves, read how FHA loss mitigation works and is FHA going away?.
What to do if you have an FHA loan and fall behind
What to watch out for, and what not to do
- Do not refuse a trial payment plan offer without reading it; a third refusal in the same default counts as a failure.
- Do not count on a second rescue: HUD allows one home-retention option every 24 months.
- Do not pay anyone up front to “stop” a foreclosure or sign your deed to them. HUD-approved counselors are free.
- Do not ignore the Rule 120 court notice in Colorado; talk to an attorney.
- Do not let a home with equity go to the sale. The auction is for the debt, not the home’s value.
For HUD home buyers: when do FHA foreclosures become HUD homes?
Slowly, and not all of them. HUD says sales trail foreclosure starts by about 5 to 10 months, and many FHA homes sell to outside bidders at or after the Public Trustee sale. The ones that go back to HUD show up on HUD Home Store. Watch HUD homes for sale in Colorado, Denver HUD homes, Aurora HUD homes and Colorado Springs HUD homes, and read how to buy a HUD home and the $100 down program. Had a foreclosure yourself? See buying after a foreclosure.
Inspector's Notes: what a foreclosed FHA home needs checked
I've sold homes in Colorado since 2003, and I spent 25 years in construction. When an FHA home goes through foreclosure and becomes a HUD home, it usually sits empty for months. These are the checks I make before a buyer bids:
More on inspections: HUD homes as-is: inspection tips, winterized HUD homes and mold and meth in HUD homes.
FHA foreclosure in Colorado: questions
How long does an FHA foreclosure take in Colorado?
HUD's FY2026 report puts the average time in foreclosure for Colorado FHA loans at 6 months. Before that, most owners are at least 4 months behind, because federal rules block the first filing until the loan is more than 120 days late.
When can an FHA servicer start foreclosure in 2026?
Under HUD Mortgagee Letter 2026-08, after at least three full monthly payments are unpaid and the loss mitigation review is finished and the borrower was told the result, or the borrower failed a loss mitigation agreement, or never responded. Federal servicing rules also require the loan to be more than 120 days late.
How many times can I get FHA help to keep my home?
HUD's 2026 rules allow one home-retention option, such as a modification or partial claim, every 24 months, and a trial payment plan comes first.
Can I sell my FHA home before the foreclosure sale?
Yes. Until the Public Trustee sale, you can sell at market value and keep any equity, or ask the servicer about FHA's pre-foreclosure sale (short sale) if you owe more than the home is worth.
Does every FHA foreclosure become a HUD home?
No. Many sell to an outside bidder at or after the foreclosure sale (HUD calls this Claim Without Conveyance of Title). Only homes that go back to HUD are listed on HUD Home Store, often months after the sale.
Where to go next
- Colorado foreclosure timeline, month by month
- Foreclosures explained · Colorado foreclosures · Denver foreclosures
- HUD homes vs occupied foreclosures · Colorado foreclosure auctions
- What is a HUD home? · Financing a HUD home · HUD home FAQs
- Own the home? Sell your home in Colorado · Stop foreclosure in Colorado · Behind on your mortgage · Short sale help
- By city: Denver · Aurora · Littleton · Parker · Fort Collins
Sources: HUD, Financial Status of the FHA Mutual Mortgage Insurance Fund, Fiscal Year 2026 (data as of September 30, 2026); HUD Mortgagee Letter 2026-08, Updates to Loss Mitigation Requirements (June 23, 2026); 12 CFR 1024.41 (federal loss mitigation rules); Colorado Revised Statutes 38-38-104 and 38-38-108 (Public Trustee cure and sale dates).
Disclosure: general information about FHA loans, FHA foreclosure timelines, HUD loss mitigation, trial payment plans, partial claims, pre-foreclosure (short) sales, deeds in lieu, Colorado Public Trustee foreclosures, notices of default and HUD homes in Denver, Aurora, Colorado Springs, Pueblo and across Colorado. The Kenna Group at Keller Williams DTC is a real estate group, not a lender, attorney, housing counselor or government agency, and is not affiliated with HUD or FHA; this is not legal, tax or lending advice. Rules and deadlines depend on your loan and your county; confirm yours with your servicer, a HUD-approved housing counselor (800-569-4287) or a Colorado attorney. Keller Williams Realty DTC, LLC. Equal Housing Opportunity.
Written and reviewed by
Brian Lee Burke, Colorado HUD home specialist and team leader
Licensed Colorado real estate professional since 2003 · REALTOR® · Team leader and licensed broker of the Kenna Group at Keller Williams DTC, a group that regularly bids on HUD homes through Keller Williams Realty DTC, LLC, a HUD-registered brokerage · Author of The Real Estate Playbook and Mastering Real Estate. Brian’s full HUD biography.
Last reviewed: November 20, 2026 · Sources: HUD Home Store (hudhomestore.gov) and HUD program guidance, HUD Handbook 4000.1, REcolorado MLS data via kennarealestate.com, and the Kenna Group’s own HUD transaction files.
Contact: call or text 303-955-4220 or homes@kennarealestate.com. During office hours you reach a live local Kenna Group real estate professional, not a robot or a national call center. Brokerage: Keller Williams Realty DTC, LLC (the Kenna Group is a group of brokers there), 6300 S Syracuse Way, Suite 150, Centennial, CO 80111. Each Keller Williams office is independently owned and operated. The Kenna Group is an independent real estate team and is not affiliated with or endorsed by HUD or any government agency; official property information comes from HUD Home Store. Equal Housing Opportunity.
Bid with your financing lined up
Get ready for a HUD bid pre-approval
HUD homes go to the best bid by the deadline, and your agent submits it for you. Answer a few quick questions and a Kenna Group agent will call to go over your numbers, the HUD financing code and the bid timeline, then line up a pre-approval with a lender if you want one. No cost, no obligation.
Free guide, PDF
$100 Down: The HUD Home Financing Guide
The $100 down rule, CHFA, HUD paying your closing costs: the stack that gets a buyer in for about $1,000. 14 pages, free.
Why you want it before you bid:
- Which listings qualify for $100 down and how to spot them (the IN and IE codes)
- What you still pay at closing, line by line, with a real example
- How $100 down stacks with CHFA, metroDPA and Good Neighbor Next Door
Find every home available, not just HUD homes
Advanced home search: every listing on the Colorado MLS, with the full filters, on kennarealestate.com.
Opens kennarealestate.com, the Kenna Group’s full MLS search. HUD homes only? Use the tiles and the map on this site.
Ask us about HUD homes
Tell us what you are working with and we will tell you honestly whether a HUD home is the way to get there. No cost, no obligation, and nobody sells you anything.
Call or text 303-955-4220
A live person answers. Not a robot, not a phone tree.