Short answer: yes, you can cancel a HUD purchase after the inspection. The contract does not stop you. What it does is decide how much of your earnest money you get back, and that depends on who you are and why you are cancelling.
There is no inspection contingency, and that is the point
A normal Colorado contract lets you inspect and walk away for any reason inside the inspection deadline with your earnest money. HUD’s contract (form HUD-9548) gives you the right to inspect within 15 days of acceptance but does not make the purchase contingent on the result. HUD sells as-is and has told you so on the listing. So the inspection is not a decision point the contract recognizes; it is information you buy so you can make a decision the contract charges for.
What cancelling costs an owner-occupant
HUD’s earnest money forfeiture policy, printed on the contract, is the rule. In general terms and with the contract controlling:
- All of the earnest money comes back if the reason is one HUD lists as outside your control and you document it: your lender denies the loan in writing for a reason that is not your fault, HUD cannot deliver clear title, or a listed hardship such as death or serious illness of a purchaser or a job loss.
- Part of it (typically half) is forfeited when an owner-occupant cancels for other reasons, which is where “the inspection found things I did not like” usually lands.
- All of it is forfeited if the buyer simply fails to close and does not follow the cancellation steps.
What cancelling costs an investor
Investors forfeit the full earnest money for cancelling for any reason other than HUD’s failure to deliver. Inspect before you bid whenever the listing allows it, because an investor’s inspection after acceptance is only ever information.
The lender denial route
The full-refund reason that comes up most is a written financing denial. If the inspection reveals a condition problem and your lender, on seeing the report, will not lend on the house, the denial letter can return all of the earnest money. It has to be a real denial for a reason not within your control; asking a lender to write one as a favor is fraud, and asset managers have seen that letter before.
How to cancel correctly
- Tell your agent immediately. Cancellation goes to the asset manager through your HUD-registered broker, in writing, with the earnest money disposition form.
- Attach the documentation for your reason: the lender’s denial, the title problem, the hardship.
- Do not just stop responding. Letting the closing deadline pass is the most expensive way to cancel, and it can affect your ability to bid on other HUD homes.
The better plan: inspect before you are on the hook
You can view a HUD home before you bid. You cannot turn on utilities before you have a contract, but a good inspector can tell you a lot about a roof, a foundation, a panel and a furnace with the power off. What to check on an as-is HUD home, and the full forfeiture rules if you do need to cancel.
Questions people ask next
Does HUD ever fix problems the inspection finds?
No. HUD sells as-is and does not negotiate repairs or credits after acceptance. The only price changes come from re-listing, not from inspection findings.
Can I cancel because the appraisal came in low?
A written lender denial tied to the appraisal can qualify for a full earnest money refund for an owner-occupant. On many HUD homes the FHA appraisal is already on file, so ask your lender about it before you bid.
How long does it take to get earnest money back?
After the asset manager approves the disposition, refunds typically take a few weeks. Incomplete paperwork is the usual reason for delay.
Can I bid on another HUD home while my cancellation is pending?
Owner-occupants usually can, but a cancellation that is treated as a default can affect future bids. Ask your agent to confirm the disposition before you submit a new bid.
The listing controls. HUD changes its procedures from time to time and every property has its own dates, codes and conditions on HUD Home Store. Where this page and the official listing or current HUD rules differ, the listing and HUD’s current rules control. We check this page regularly; ask us to confirm anything before you rely on it.
Looking at a specific HUD home? Call or text 303-955-4220. A HUD-registered agent answers, reads the listing with you, and the answer is free.
Written and reviewed by
Brian Lee Burke, Colorado HUD home specialist and team leader
Licensed Colorado real estate professional since 2002 · REALTOR® · Team leader and licensed broker of the Kenna Real Estate Group at Keller Williams DTC, a HUD-registered group that regularly bids on HUD homes · Author of The Real Estate Playbook and Mastering Real Estate. Brian’s full HUD biography.
Last reviewed: September 20, 2026 · Sources: HUD Home Store (hudhomestore.gov) and HUD program guidance, HUD Handbook 4000.1, REcolorado MLS data via kennarealestate.com, and the Kenna Real Estate Group’s own HUD transaction files.
Contact: call or text 303-955-4220 or homes@kennarealestate.com. During office hours you reach a live local Kenna real estate professional, not a robot or a national call center. Brokerage: Kenna Real Estate Group at Keller Williams Realty DTC, LLC, 6300 S Syracuse Way, Suite 150, Centennial, CO 80111. Each Keller Williams office is independently owned and operated. The Kenna Real Estate Group is an independent real estate team and is not affiliated with or endorsed by HUD or any government agency; official property information comes from HUD Home Store. Equal Housing Opportunity.
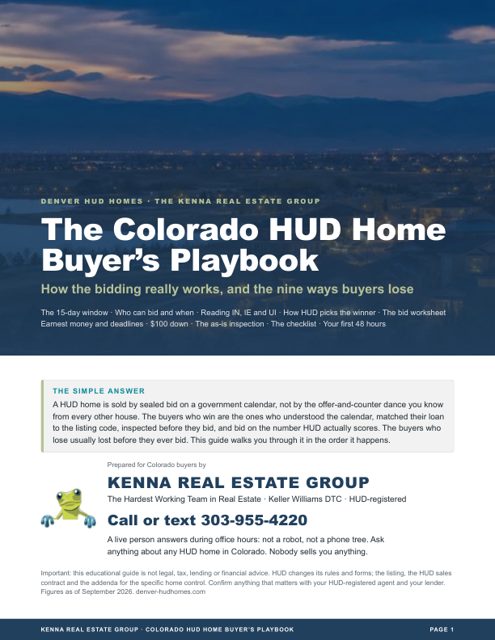
Free guide, PDF
The Colorado HUD Home Buyer's Playbook
How HUD bidding really works, the nine ways buyers lose, and the bid worksheet. 18 pages, free.
Why you want it before you bid:
- The 15-day owner-occupant window, day by day, so you never miss a deadline
- The net-to-HUD math HUD actually scores, with a one-page bid worksheet
- The nine ways buyers lose a HUD home, and how each one is avoided
Find every home available, not just HUD homes
Advanced home search: every listing on the Colorado MLS, with the full filters, on kennarealestate.com.
Opens kennarealestate.com, the Kenna Real Estate Group’s full MLS search. HUD homes only? Use the tiles and the map on this site.
Ask us about HUD homes
Tell us what you are working with and we will tell you honestly whether a HUD home is the way to get there. No cost, no obligation, and nobody sells you anything.
Call or text 303-955-4220
A live person answers. Not a robot, not a phone tree.